ICPAK warns Saccos against SASRA’s directive on Sh12.5 billion lost in KUSCCO heist
Accountants body notes that the law requires them to prescribe an asset review system that accurately identifies risks and assures the adequacy of provisions for losses

The Institute of Certified Public Accountants of Kenya (ICPAK) has warned Savings and Credit Co-operative Societies (Saccos) against flouting International Financial Reporting Standards (IFRS) in providing for losses they are likely to suffer as a result of the Ksh 12.5 billion Kenya Union of Savings & Credit Cooperatives (KUSCCO) scandal.
In an advisory to the Saccos, ICPAK chairman Philip Kakai said they should not adhere to a January 24 guideline by the Sacco Societies Regulatory Authority (SASRA) to immediately start recognising impairment losses and make provisions for future write offs that would arise from the said financial investments in the financial statements.
While noting that since its establishment, SASRA has prudently steered the Sacco Sector in Kenya through prudent regulation, supervision, promotion of the sector and protection of members’ interests, Kaikai said ICPAK was concerned with the contents of the guideline relating to financial investments and / or deposits held by the regulated Saccos in KUSCCO, saying it requires further clarity.
He said the IFRS are clear on how Saccos should undertake the process to avoid flouting international standards, which will come with severe consequences for both Saccos and ICPAK.
“To ensure the preparers and auditors of SACCOs are well guided in adherence to the requirements of IFRS, specifically IFRS 9 – Financial Instruments; ICPAK issues this guidance in line with its mandate as the Regulator and Standard Setter of the Accountancy Profession, bestowed with the role of issuing guidance on professional practice and adoption of financial reporting and auditing standards in Kenya,” Kakai said in the advisory.
He noted that in the recent past, KUSCCO Ltd has been reported to be facing financial challenges resulting in its likely inability to meet its obligations. This would impact the financial assets held with KUSCCO by its member Saccos, including but not limited to deposits placed and equity investments.
While advising against implementing the SASRA guideline, he said that Section 33 (3b) of the Sacco Societies Act, 2008 requires Saccos to prescribe an asset review system that accurately identifies risks and assures the adequacy of provisions for losses while IFRS 9 provides comprehensive guidance on the recognition and measurement of financial investments including recognition of expected credit losses (ECL) on financial assets such as those placed in KUSCCO as well as fair value judgement on the carrying value of equity investments in KUSCCO.
He went on to guide that IFRS 9 prescribes the Expected Credit Loss (ECL) model, which mandates a forward-looking approach to impairment provisioning.
Three-stage impairment model
Thus, Saccos must evaluate their exposure to KUSCCO related loss event and assess the associated credit risk to determine the appropriate classification under IFRS 9’s three-stage impairment model. This determination should be based on all the information and facts available on the date of the approval of the financial statements that provide evidence of the credit quality of the balances as of the reporting date.
“IFRS 9 also requires the measurement of equity investments such as those that may be held in the form of share capital investments in KUSCCO. It is possible that management of one SACCO may make a different judgement from the management of another SACCO especially given that the level of final conclusive information on the state of affairs of KUSCCO is still an evolving matter. Such judgements would depend on materiality, information available as of the date of the approval of the financial statements and other relevant factors,” said Kakai.
On assessment of credit risk and staging of financial assets to determine ECL, Kakai said Saccos must evaluate the credit risk associated with funds placed with KUSCCO, establishing whether there has been a significant increase in credit risk (SICR).
He added that in line with IFRS 9, financial assets should be classified into one of three stages:
- Stage 1: Performing assets with no significant deterioration in credit risk, requiring recognition of 12-month ECL.
- Stage 2: Assets exhibiting a significant increase in credit risk, necessitating recognition of lifetime ECL.
- Stage 3: Credit-impaired assets, lifetime ECL with probability of default (PD) at 100%. Loss Given Default (LGD) has increased significantly, full recovery may be unlikely.
Kakai said that the Saccos must estimate ECL based on a combination of historical data, current asset-specific and macro-economic conditions, and forward-looking information, adding they should determine the staging classification of funds placed with KUSCCO in line with the factors described above and make the requisite ECL provisions.
He also noted that IFRS 7 mandates detailed disclosure of credit risk exposure, the methodology used in estimating ECL, and the financial impact of credit deterioration. IFRS 7 also requires disclosure of fair value related measurements for equity investments and other Financial Assets measured at fair value.
Further, Saccos must ensure comprehensive disclosure in their financial reports, explicitly detailing assumptions, judgments, and the rationale behind provisioning decisions.
They must also determine whether events occurring after the reporting date are adjusting or non-adjusting events in line with the provisions of IAS 10, which provides that if new information arises before the financial statements are authorised for issue that provides evidence of conditions existing at the reporting date, Saccos must adjust the recognised amounts of assets and liabilities accordingly.
If the events occurred after the reporting date and do not provide evidence of conditions existing at that date, it should not lead to an adjustment in the financial statements.
However, he said, Saccos must disclose the nature of the event, an estimate of its financial “impact, or a statement indicating that such an estimate cannot be made.
“In the case of KUSCCO, the same is likely to be considered an adjusting event for all Saccos reporting as at 31 December 2024 with investments, savings and deposits with the entity based on the definitions above. Therefore, information received after the reporting period may be relevant in determining the staging of such financial assets as at the reporting date and therefore determining the ECL provisions and the fair value of equity investments as applicable,” said Kakai.
Perils of non-compliance
“Non-compliance with IFRS may result in qualified auditors’ opinions on the financial statements of SACCOs in Kenya where such non-compliance has a material impact. This would seriously undermine public trust and expose the SACCOs to regulatory, legal, financial and operational risks. Additionally, non-compliance would undermine the good standing status of ICPAK as a member of the International Federation of Accountants (IFAC) in turn affecting the global professionalism and practice including recognition of the Kenyan accountants across other jurisdictions,” he added.
Kakai revealed that ICPAK will organise a joint session with SASRA to discuss the above in a bid to provide clarity and guidance to the preparers and auditors and ensure compliance in the foregoing reporting period, while assisting SASRA to further enhance the regulation of the Sacco sector in Kenya in pursuit of public interest.
However, some of the leading Saccos are already said to have implemented the guideline by making provision for the expected losses in their 2023/24 financial statements, in the process going against accounting rules.
But others have moved to court to challenge SASRA’s directive accusing it of seeking to defend KUSCCO officials accused of executing the multi-billion shillings fraud.
A forensic audit by PwC revealed how top executives siphoned the Ksh 12.5 billion belonging to various Saccos, with top officials cooking the financial books to reflect fictitious profits and dividends, yet it was on the verge of collapsing. They even forged a dead man’s signature.
Former Managing Director George Ototo, Finance Manager George Owino, and KUSCCO chairman George Magutu, who are at the centre of the fraud, concealed Ksh 6.5 billion in internal loans, Ksh 1.6 billion commission, Ksh 3.7 billion hidden transactions, and Ksh 9.3 billion misstated accounts, in addition to a misstated Ksh 6.5 billion in internal loans.
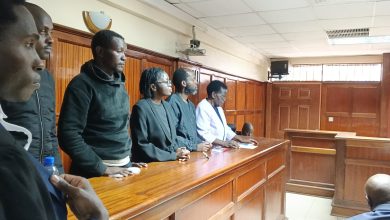
After retrieving a trove of incriminating information from the emails, M-Pesa statements, and computer logins of 23 directors at KUSCCO, PwC spotlighted eight executives, placing them at the centre of the circus with four already presented in court.
The PwC reports reveal that the officials inflated the assets of KUSCCO, pocketing Sh206 million each in unexplained withdrawals, which they lied were used to refurbish its branch.
The officials did all this to advocate, train, and lobby for the extension of deposits by Saccos.
The audit unmasked Ksh 1.2 billion paid to contractors where only two out of the 16 contractors of the Kitengela project signed the agreements with questionable credibility.