CoB flags legal gaps in Kenya’s oil revenue oversight, calls for stronger safeguards

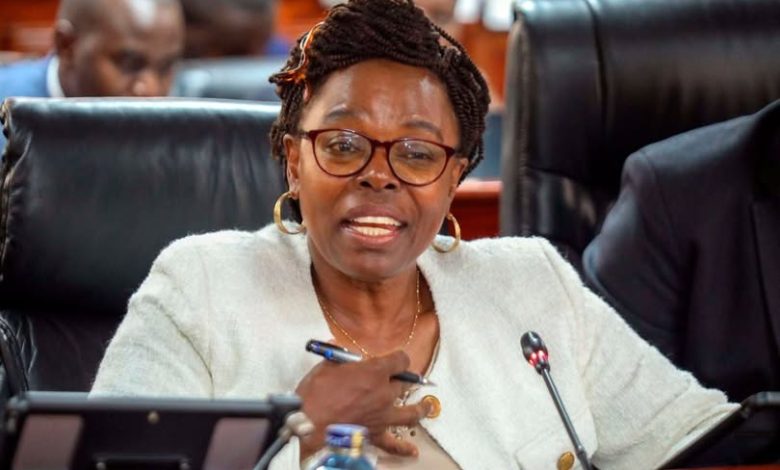
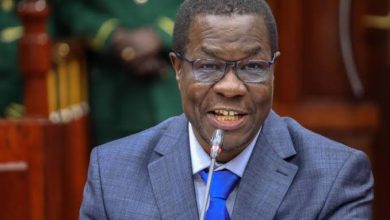
Kenya’s oil revenue management framework faces critical legal and policy gaps that, if unaddressed, could undermine transparency, accountability, and equitable benefit sharing from the country’s burgeoning petroleum sector, the Controller of Budget (CoB) Dr. Margaret Nyakang’o has warned.
In her report to the Joint Senate Standing Committee and National Assembly Departmental Committee on Energy on Wednesday, February 11, 2026, the CoB highlighted the loopholes in legislation governing the collection, utilisation, and monitoring of oil revenues, as well as profit sharing arising from crude oil development and export.
Speaking before the Joint Committee Nyakang’o flagged the limited disclosure of petroleum agreements, including Production Sharing Contracts (PSCs), which hampers public accountability.
“There is a lack of precise mechanisms for monitoring the 5 per cent share of royalties intended for local communities. This ensures that the 5 per cent local community share is managed via a legally constituted, locally appointed Board of Management to prevent misuse,” she noted.
Nyakang’o’s report also revealed that there is currently no statutory mechanism to safeguard oil revenues for future generations.
Presently, proceeds from crude oil activities may be applied to immediate operational expenditures without guarantee that a portion is saved for long-term national benefit. She argued that her office should play a central role in overseeing the distribution and utilisation of petroleum revenues accruing to both national and county governments.
Article 228(4) of the Constitution mandates the CoB to oversee the implementation of national and county budgets.
This oversight involves authorising withdrawals from public funds, including the Consolidated Fund, County Revenue Funds, and the Equalisation Fund, only when legally permissible.
Section 57(1) of the Public Finance Management Act, 2012, prescribes that the national government’s share of petroleum revenues, prior to tax imposition, be deposited into a dedicated Petroleum Fund, managed in line with the Act.
Meanwhile, the local community’s share is to be deposited into a trust fund managed by a board of trustees established in consultation with the relevant county government and community.
However, Nyakang’o told MPs that the law does not clearly define how county governments are to spend their 20 per cent share of petroleum revenues, nor does it provide the CoB with unambiguous authority to authorise withdrawals of these funds.
“The mandate of the CoB in authorising withdrawal of funds from oil revenue arising from crude oil activities should be provided clearly in the Petroleum Act and Regulations,” she said.
Under the Petroleum Act, 2019, profit from upstream petroleum operations is apportioned among the national government, county governments, and local communities at 75 per cent, 20 per cent, and 5 per cent, respectively.
The CoB boss emphasised that the Ministry of Energy and Petroleum should be legally compelled to submit quarterly reports on both financial and non-financial performance of oil fields, including the T6 and T7 blocks in the Lokichar Basin, Turkana County.
“My office will then analyse this information and provide quarterly reports to Parliament and County Assemblies through the Budget Implementation Review Reports,” she said.
Auditor General Nancy Gathungu reinforced the CoB’s concerns, highlighting that Kenya, despite having a legal petroleum management framework, is not a member of the Extractive Industries Transparency Initiative (EITI). EITI membership requires disclosure of beneficial ownership the identities of individuals controlling companies bidding for oil blocks and adherence to international standards for transparency in high-risk extractive industries.
“Non-membership of the EITI means that the country does not adhere to the rigorous public register standards specifically designed for extractive industries,” Gathungu told MPs.
She added that this exposes Kenya to higher governance risk premiums in international markets, potentially raising borrowing costs for energy infrastructure projects.
Furthermore, international lenders and institutional investors use compliance with EITI and related standards as key metrics for Environmental, Social, and Governance (ESG) scoring, making transparency essential for sustainable investment.