Questions swirl over secretive sale of NSSF’s EAPC shares to Kalahari

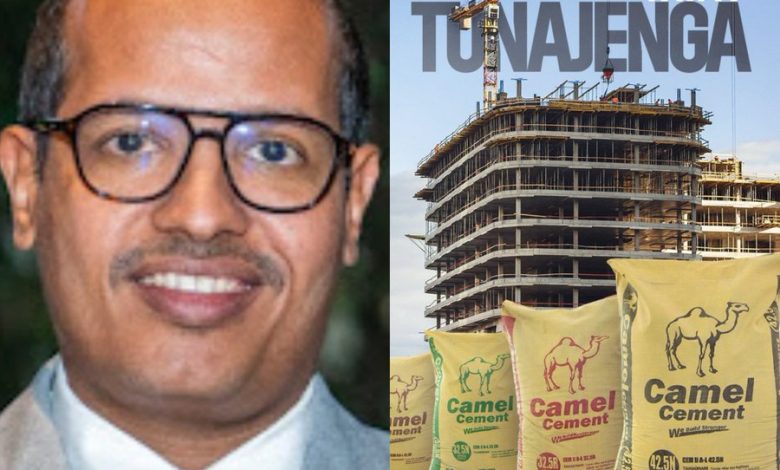
The opaque sale of the National Social Security Fund’s (NSSF) 27 per cent shareholding in East African Portland Cement (EAPC), a publicly listed company on the Nairobi Securities Exchange (NSE) under the ticker symbol PORT to Kalahari Cement Limited, a subsidiary of a subsidiary of Amsons Group has ignited fresh suspicion over possible insider dealings, undervaluation and a coordinated attempt to mask the ultimate value of assets NSSF held at EAPC.
The controversial deal has seen the Consumer Federation of Kenya (COFEK) move to the High Court seeking urgent conservatory orders to stop the ongoing acquisition by Kalahari which is owned by Tanzanian Tycoon Edhah Abdallah Munif, citing alleged violations of constitutional rights and major regulatory gaps.
COFEK claims that the move has proceeded without full public disclosure, regulatory transparency, or demonstrable compliance with the Capital Markets Act, the Competition Act, the Public Finance Management Act, and applicable governance standards.
“Unless this Honourable Court intervenes urgently, the sale and transfer of NSSF shares to Kalahari Cement Limited may be completed imminently, resulting in irreversible consolidation of ownership and control, loss of public leverage, and rendering the present petition academic and nugatory,” the lobby group said in court documents.
NSSF has since signed the sale agreement 24.3 million shares translating to 27 per cent of its stake at EAPC at Sh1.6billion.
The acquisition, which follows Kalahari’s previous 29.2 percent purchase from other shareholders, will result in Kalahari Cement and its affiliates holding an effective 68.7 percent controlling stake in EAPC.
When contacted by The Informer Media Group, NSSF Managing Trustee David Koross did not respond to our queries regarding the worth of the assets NSSF held in its stake at EAPC and whether they were computed as part of the value of the shares sold.
COFEK is now questions the transaction executed quietly and without public disclosure or competitive bidding.
Instead, the deal appears to have been fast-tracked through a narrow circle of decision-makers, raising questions about who authorised the divestiture, why it was done in secrecy, and whether the workers’ retirement fund received value for money.
In the petition filed at the Milimani Constitutional and Human Rights Division, COFEK accuses the Capital Markets Authority (CMA), the Competition Authority of Kenya (CAK), the National Social Security Fund (NSSF), and other respondents of failing to ensure transparency, due diligence, and regulatory compliance in the high-stakes transaction.
COFEK argues that the acquisition, carried out through the purchase of government-owned and NSSF shares, raises concerns over consumer protection, market dominance, and the legality of the processes used.
Further, the petitioner claims that the transaction threatens the constitutional rights of Kenyans under Articles 35, 40, 47, and 50 relating to access to information, property rights, fair administrative action, and fair hearing.
The consumer body is therefore seeking a series of orders, including restraining CMA, CAK, NSSF, Kalahari Cement, and East African Portland Cement from transferring, consolidating, or exercising voting rights linked to the disputed shares.
COFEK is also seeking orders to compelling the Capital Markets Authority to conduct a full compliance inquiry into the transaction and orders directing the Competition Authority to carry out a merger and competition assessment to determine whether the acquisition could create dominance, monopoly risks, or anti-competitive conduct.
The petitioner argues that the transaction would result in effective foreign control or majority influence over EAPC, a strategic Kenyan cement manufacturer with a history of State ownership and national economic importance.
If the deal goes through, Kalahari and its parent company, Amsons Group, will have a controlling stake in EAPC once regulatory approvals are in place.