Court stops prosecution of bank CEOs in Sh363million fraud
For six years, hundreds of millions of shillings allegedly stolen from a company were moved through the accounts of three of Kenya’s biggest banks; KCB, Co-op Bank and NCBA with investigators now asking a potentially explosive question over how the banking system failed to stop or report the suspicious transactions.

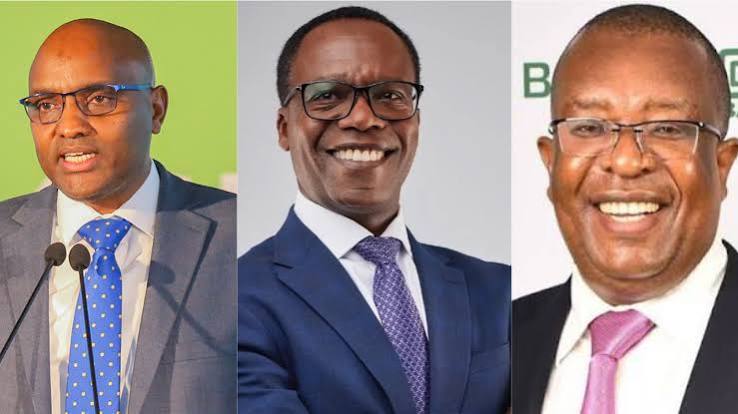
The court has stopped planned prosecution of three top banks executives over allegations that their institutions failed to report suspicious transactions linked to an alleged Sh363 million fraud at First Assurance Investment Company Limited.
NCBA Bank Chief Executive Officer John Gachora, KCB Bank Kenya CEO Paul Russo and Co-operative Bank Group Managing Director Gideon Muriuki had been summoned to appear before Milimani Chief Magistrate Gethi Kibiru on August 11, 2026 over alleged breaches of obligations imposed on financial institutions under the Proceeds of Crime and Anti-Money Laundering Act (POCAMLA).
The case has put the spotlight on the responsibility of banks to detect and report suspicious transactions and raised fresh questions about whether weaknesses in financial institutions’ compliance systems can allow proceeds of alleged fraud to move through the banking system undetected.
According to the charge sheet presented in court, the three bank executives face multiple counts relating to the alleged failure to report suspicious transactions involving proceeds of crime.
The Office of the Director of Public Prosecutions (ODPP) says the CEOs will be charged with failure to report suspicious transactions regarding proceeds of crime, contrary to Section 5 as read with Section 44(2) of POCAMLA.
The prosecution alleges that the offences were committed on different dates between May 18, 2018 and April 30, 2024.
The case stems from allegations against Salim Mohamed Busaidy, a former nominated Member of the County Assembly and former director of First Assurance Investment Company Limited.
Busaidy is accused of stealing Sh363,320,459 belonging to the company by exploiting his position as a director and his access to its bank accounts held at NCBA Bank, KCB Bank and Co-operative Bank.
Investigators allege that Busaidy forged the signature of his co-director, Issa Abdalla Issa Timamy, the Lamu Governor, on multiple company cheques.
The forged cheques were allegedly presented as genuine and duly authorised, enabling withdrawals from the company’s accounts.
The charge sheet shows that the cheques were for various amounts, ranging from Sh150,000 to Sh350,000.
The prosecution further alleges that Busaidy acquired Sh363,320,459 knowing that the money constituted proceeds of crime arising from the alleged theft.
Busaidy has denied 120 charges, including conspiracy to defraud, stealing, 114 counts of making a document without authority and one count of acquisition of proceeds of crime.
He was released on a Sh10million bond with one surety of a similar amount, or a cash bail of Sh3million.
The prosecution’s case against the banking executives centres not necessarily on an allegation that they personally participated in the theft, but on whether their institutions fulfilled their statutory obligation to identify and report suspicious transactions.
Under POCAMLA, reporting institutions such as banks are required to monitor transactions, identify suspicious activity and report it to the Financial Reporting Centre (FRC).
Section 5 of the Act provides that a person who wilfully fails to comply with an obligation contemplated under Section 44(2) commits an offence.
A conviction could attract imprisonment for a term not exceeding seven years, a fine of up to Sh2.5 million, or both.
The case has revived memories of an earlier regulatory crackdown involving some of the country’s largest lenders over the Sh10.5 billion National Youth Service (NYS) scandal.
In 2020, KCB, Equity Bank, Co-operative Bank, Standard Chartered Bank and Diamond Trust Bank paid a combined Sh385 million in fines for failing to detect and report suspicious transactions linked to the scandal.
The banks were found to have breached provisions of POCAMLA after fraudulent payments were processed through their systems.
The NYS scandal involved the alleged siphoning of billions of shillings from the institution over approximately three years through a scheme involving senior government officials and ghost suppliers.
A probe established that the banks had failed to maintain effective anti-money laundering programmes and conduct sufficient due diligence on some account holders.
The lenders were not accused of being directly involved in the graft but were faulted for failing to report suspicious transactions.
The regulatory action resulted in demands for banks to strengthen their “know your customer” (KYC) procedures, ensure proper supporting documentation for transactions and enhance their anti-money laundering and combating financing of terrorism monitoring systems.
Banks were also expected to adopt technology capable of real-time monitoring of digital transactions.
The latest case has nevertheless raised the stakes because the prosecution has moved against senior executives over alleged compliance failures.
Analysts say banks can inadvertently facilitate fraud through weak internal controls, insider collusion, delayed technological upgrades or lax customer onboarding processes.
Such weaknesses, they argue, can allow illicit funds arising from corporate theft, fraud or shell companies to move through the financial system without being detected in time.
Other cases have also exposed the financial risks arising from alleged failures in banking controls.
In March, the Court of Appeal allowed Equity Bank to auction the former headquarters of Chase Bank, which is under liquidation by the Kenya Deposit Insurance Corporation (KDIC), over a Sh1.3 billion facility allegedly acquired using misappropriated depositor funds.
The liquidated bank had sought to preserve the property pending a separate recovery case against its former directors, led by former chairman Zafrullah Khan.
Family Bank, meanwhile, has previously opted for plea bargains with the ODPP, admitting charges relating to failure to report statutory cash disclosures and paying penal fines.
The scale of suspicious activity reported to regulators illustrates the challenge facing the financial sector.
According to the FRC’s 2024 annual report, the centre received 8,057 reports from reporting institutions and whistleblowers. These included 5,454 suspicious transaction reports, 2,482 suspicious activity reports and 114 suspicious transaction activity reports, alongside seven reports from walk-ins and whistleblowers.