Business conditions weaken further as protests and low spending hit sales, survey shows
Despite headwinds, Kenyan firms displayed increased optimism about prospects, as sentiment levels reached their highest since May 2024

The Kenyan Private Sector faced additional challenges in the first half of 2025, according to the latest Stanbic Bank Purchasing Managers’ Index (PMI)
Headline figures derived from the survey indicate that the dipped by one more mark lower than the 49.6 recorded in May, signalling a modest decline modest decline in business conditions that was the sharpest in 11 months.
According to the survey by the banker, weaker conditions were primarily driven by a solid contraction in business activity.
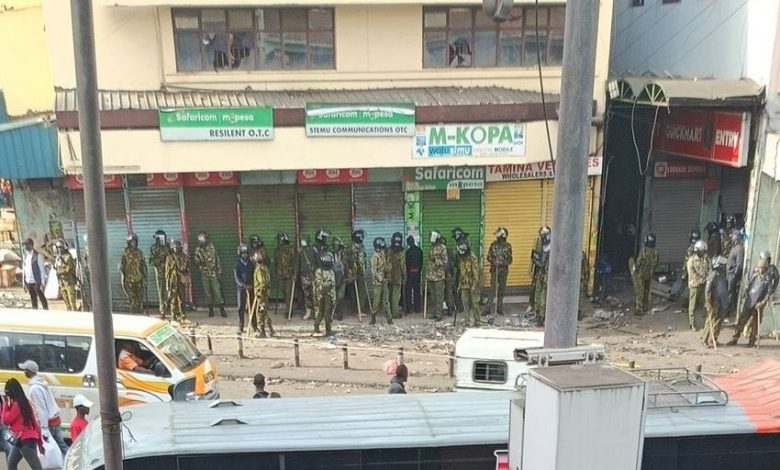
Survey respondents attributed this decline to lower customer spending, challenging economic conditions, and operational disruptions due to protests witnessed twice during the month.
The downturn was compounded by a steeper fall in new orders, with over one-third of surveyed businesses reporting reduced sales intake, compared to only 20 per cent noting an expansion.
Firms consistently cited difficult conditions for clients as the main factor behind diminishing new business.
Despite these headwinds, Kenyan firms displayed increased optimism about prospects, as sentiment levels reached their highest since May 2024.
Approximately 18 per cent of respondents expressed confidence in their ability to boost output over the next year, citing expectations of improved sales and market expansion.
This optimism represented a marked improvement from the muted sentiment levels recorded earlier in the year.
Employment conditions were also a bright spot, with staffing levels rising for the fifth consecutive month, albeit only marginally.
Delivery times in June improved at the fastest rate in nearly two years, driven by heightened competition and reduced road congestion.
However, some firms still experienced delays due to port clearance issues and material shortages.
Kenyan businesses ramped up stockpiling during the month, with inventory levels rising at the sharpest rate since October 2022.
This reflected both optimistic demand forecasts and strategic purchases taking advantage of favorable material prices.
Despite this, overall purchasing activity declined, posting the steepest drop since July 2024, as firms adjusted their procurement in response to softer sales.
On the pricing front, input cost pressures intensified, with overall input inflation reaching its highest level since January.
The main driver was increased salary expenses, while purchase price inflation eased to a four-month low.
Output prices rose only slightly, as firms sought to recover costs without losing customers in a still-challenging market environment.
“Input prices, purchase prices, staff costs, and output prices all increased in June but only matched, or came below, the long-term average, implying that inflationary pressures are both low and contained. Price increases reflect concerns about the increased tax burden being faced by businesses,” Christopher Legilisho, an Economist at Standard Bank, commented.